- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted September 8, 2026 at 1:23 pm
Escalating geopolitical tensions in the Middle East are dampening investor sentiment on Wall Street, as rising crude prices place inflation risk at the forefront of the fixed-income conversation just as critical PPI and CPI reports are scheduled to hit the wire on Thursday and Friday. Those heavier energy costs, which are almost reaching $95 per barrel on WTI, are driven by a resurgence in violence near the Strait of Hormuz and are lifting yields, as participants gear up for a potential change in monetary policy at the Fed’s decision in only eight days. Emblematic of the hawkish interpretation is the Treasury curve climbing in bear-flattening motion guided by the shorter tenors, as odds of a 25-bp September increase from the Warsh led central bank are now at 59%. Additionally, this morning’s small business optimism results from the NFIB declined and missed expectations due to the sour backdrop of lofty fuel charges, burdensome credit expenses and tariff uncertainty adversely impacting entrepreneur earnings trends, economic outlooks, capital expenditure prospects and hiring plans. Those tighter financial conditions are weighing on stocks too as the four major equity benchmarks retreat amidst 7 of the 11 principal sectors suffering losses. Precious metals and cryptocurrencies are also declining with an increasingly restrictive liquidity environment hampering demand for non-interest-bearing gold, silver and bitcoin. Still, volatility protection instruments and the greenback are nearly flat while prediction markets are catching bids.
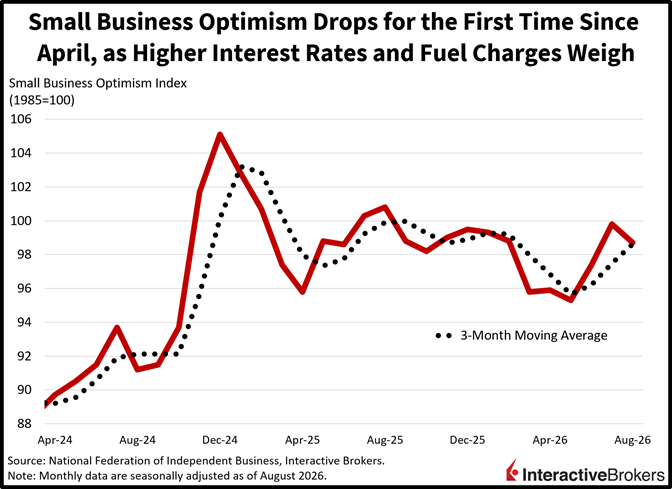
Pricey oil and elevated interest rates matter more for smaller firms than for their larger counterparts, as they generally have fewer levers to pull to offset macroeconomic pressures. The increasingly challenging backdrop drove the first decline in the National Federation of Independent Business’s (NFIB) Optimism Index since April, as August’s result of 98.7 missed the median estimate of 99.3 and sank from July’s 99.8. Survey respondents reported a worsening economic outlook, decelerating earnings, a decrease in capital expenditure plans and softening hiring prospects amidst broad-based weakness across segments. Meanwhile, 23%, 16% and 16% of poll answers signaled that the quality/availability of labor, inflation and taxes were their single most important problem.
Used car prices dropped for the second consecutive month in August, hitting the lowest level since December. Indeed, aggregate values fell 0.9% month over month (m/m) after slipping 1.4% in July, while the annualized year-over-year (y/y) increase decelerated from 1.3% to 0.4%. Electric automobiles saw stickers fall 4.7% m/m while combustion engines slipped just 0.6%; however, the y/y changes signal a 4.5% gain for the former amidst a 0.9% decrease for the latter, as higher fuel costs incentivized the transition away from gasoline powered vehicles.
Progress on inflation is poised to reverse if geopolitical tensions don’t simmer. While this Friday’s read is expected to come in at 3.4%, repeating July’s number which decelerated from June’s 3.5% and May’s 4.2%, September will feature a figure in the high 3s if West Texas Intermediate (WTI) doesn’t fall to under $90 per barrel soon. Such a development would certainly warrant an interest rate hike by a Federal Reserve that has been patiently waiting for fuel prices to cool so that headline cost forces could plunge to where the cooperating core indicator, which excludes food and energy, sits in the low 2s. With yields soaring and last week’s blockbuster jobs report signaling robust hiring momentum, the committee will be focusing in on upcoming economic data to influence which way to vote, and a hotter-than-anticipated result at 3.5% or 3.6% would almost surely raise the odds of a 25-basis point (bp) lift back towards 75%. Meanwhile, a publication that misses projections could justify another pause by the central bank, as a 3.3% statistic would signal ongoing improvements in quelling price pressures.
A 25% y/y increase in exports pushed China’s trade surplus from $112.5 billion in July to $119.1 billion last month. The growth rate of shipments abroad matched the economist consensus estimate while the trade surplus exceeded the anticipated $118.6 result.
August shipments to the US sped up from July’s 17.1% y/y rate to 34.3%. Imports from the US, however, grew only 17.8% last month. Growth in exports to the European Union moved in the other direction, with growth slowing from 16% to 6.6%. China’s total imports also expanded with a 28.2% y/y increase. The consensus of economists pointed to a 29.1% northward rate following July’s 27.5% rise. While China’s trade surplus has benefited from increased demand for renewable energy technology in response to higher oil and natural gas prices, the buildout of data centers and AI infrastructure has allowed the country to benefit from its high-tech manufacturer of computer components.
South Korea’s gross domestic product during the second quarter was up 0.6% relative to the first three months of the year and 3.7% higher y/y, according to the Bank of Korea. Both metrics matched the economist consensus estimates. The quarter-over-quarter rate slowed from 1.7% in the January through March period while the y/y print accelerated from the first quarter’s 3.6% pace.
Stronger demand for computer, electronic and optical products caused manufacturing production to ascend by 1.4% from the first quarter’s level. In the service sector, activity grew 1%, a result of a rise in activity in the following categories:
Agriculture, forestry and fishing was a headwind, with production sinking 7.2%. A drop in civil engineering, furthermore, pulled construction productivity down 1.9% while the electricity, gas and water supply component was 0.6% below the first-quarter result.
On a positive note, exports ascended by 1.3%, largely due to semiconductors and machinery. Imports were up 0.7% with increased demand for motor vehicles and machinery.
Retail sales in Singapore posted a 1.5% y/y advance during July after jumping 5% in June. Even with the slower y/y print, sales growth on a m/m basis matched June’s 0.9% print.
For the m/m result, the following categories and the extent of the sales changes experienced the strongest gains:
Petrol service stations and the category of computer and telecommunications equipment were the largest headwinds with the value of transactions slipping 7.2% and 4.7%. Transactions also sank by 4.5% and 2.7% for the food and alcohol group and the cosmetics, toiletries and medical goods category.
New to Interactive Brokers?
Open AccountInformation posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from IBKR Macroeconomics, an affiliate of Interactive Brokers LLC, and is being posted with its permission. The views expressed in this material are solely those of the author and/or IBKR Macroeconomics and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
Futures, event contracts, and forecast contracts are not suitable for all investors. Before trading these products, please read the CFTC Risk Disclosure. For a copy, visit our Warnings and Disclosures Page.
Investments in certain commodities (precious metals) may be subject to significant price volatility and often involve risks related to market fluctuations, liquidity constraints, geopolitical events, and changes in global economic conditions that could adversely affect their value.
Trading in digital assets, including cryptocurrencies, is especially risky and is only for individuals with a high risk tolerance and the financial ability to sustain losses. Eligibility to trade in digital asset products may vary based on jurisdiction.
Related Articles




Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!