- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted September 17, 2026 at 1:23 pm
Wall Street is firing on all cylinders today as market participants cheer the Federal Reserve’s first rate hike in three years. Treasurys are rallying as the front-end celebrates that yesterday’s updated dot-plot signaled just one more 25-bp increase in this tightening cycle while duration is benefiting from sinking inflation expectations because fixed-income observers increasingly believe that Chair Warsh and the committee are taking the price side of the monetary policy authority’s dual mandate seriously. The geopolitical arena also threw an assist to government debt assets as diminishing Saudi oil supply worries coincided with the potential resumption of Middle East peace negotiations between President Trump and Gulf leaders this Tuesday at the UN General Assembly. Indeed, the news sent WTI crude below $100, its lowest level in six days. Economic data were mixed, however, with a 32-month low on continuing unemployment claims and lighter-than-anticipated initial applications depicting strengthening labor momentum, although weaker-than-expected housing starts, building permits and pending home sales illustrated a prolonged real estate downturn, with activity especially frozen against the backdrop of the 30-year mortgage trading at a 7-handle. Additionally, the Bank of England’s decision to pause its balance sheet reduction program offered a sense of stability for the credit landscape, as bond watchers perceive that other global policymakers will try to support longer-dated sovereign paper, resulting in the tail of the yield curve outperforming the shorter tenors. The looser financial conditions are bolstering stocks, digital assets and non-energy commodities, as all major equity domestic benchmarks, the 11 principal sectors and subcategories, cryptocurrencies, precious metals and cyclical inputs appreciate on the session. Conversely, the greenback is depreciating in response to softer borrowing costs, premiums for volatility protection instruments are falling due to the risk-on spirits and prediction markets are catching bids.
Pending home sales last month barely rose from the bottom end of the metric’s recent statistical range, as lofty valuations alongside 7-handle mortgages weighed on affordability nationwide. The gauge posted a 0.3% month-over-month (m/m) increase amidst a 4.7% year-over-year (y/y) decline in August, which was worse than the 2% m/m gain expected. In July, sales contracted 2.6% m/m and 2.2% y/y. Despite the monthly headline advance, the Northeast and Midwest registered m/m subtractions of 4.2% and 1.6%, although they were countered by 3% and 2.3% climbs in the West and South. Contract signings are a leading indicator to closings because paperwork is usually prepared 30 days before lending terms and inspections are finalized and keys are exchanged.

Construction activity contracted in August and missed expectations, further dimming hopes for a real estate recovery in the near future. Multifamily especially underperformed, as weakening rental growth prospects caused, in party, by restrictive immigration policies, weighed on builder appetites to develop fresh dwellings. August Housing Starts and Building Permits came in at 1.275 million and 1.394 million seasonally adjusted annualized units, below the 1.31 million and 1.41 million projected and July’s 1.309 million and 1.433 million. For the former, it was amongst the weakest numbers since the pandemic recession in 2020. The pace for the apartment building asset class dropped 22.5% and 3.1% throughout the two categories, while singles rose 7.6% m/m for starts but declined 1.8% for permits. From a regional perspective, three out of four posted decreases in both indicators but the West grew 32.4% m/m in starts and 1.6% m/m in permits.

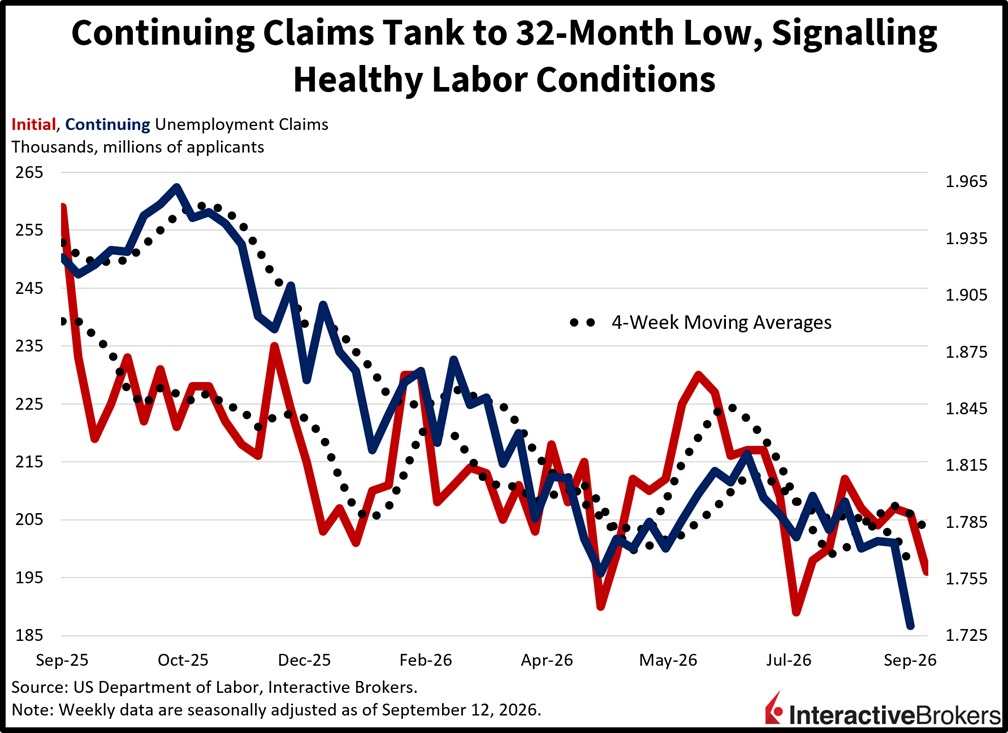
Labor conditions appear to be strengthening with unemployment claims reported today coming in lighter than expected across segments and continuing a downward longer-term trajectory. Ongoing filings plunged to a 32-month low of 1.730 million during the week that ended Sept. 5, below the 1.780 million expected and the 1.769 million from the prior period. Initial applications sank too, dropping to 196k throughout the 7-day interval culminating on Sept. 12 and arriving beneath the 208k median estimate and the 206k from the previous publication. Four-week averages fell on both fronts, from 206k and 1.779 million to 203.25k and 1.762 million, indicating the potential for a fresh acceleration in employment that could even counter the possible adverse effects stemming from the Fed’s tightening cycle.
Yesterday’s dot-plot envisions only one more hike during this tightening cycle, but the short end of the Treasury complex is pricing in about three, offering bifurcated perceptions of future monetary policy actions. At this juncture, maturities across the curve appear undervalued, as core inflation of just 2.4% signals that price pressures will plunge towards target once the geopolitical picture improves. But if fixed-income observers aren’t convinced that oil costs will decline soon, an important question for bond bears is how many quarter-percentage increases can we get from this Warsh Fed? If the answers is two or fewer, then owning government debt assets makes an incredible amount of sense because credit would have several paths to meaningful gains, including plunging inflation, peace in the Middle East or a Fed that doesn’t raise an additional 75-bps from its current midpoint of 3.87%.
Bank of England policymakers this morning voted 6 to 3 to maintain the organization’s key interest rate at 3.75%, believing that high bond yields are already restricting economic growth. Policymakers also said they believe that elevated oil and natural costs resulting from the Middle East conflict have yet to increase prices for consumer items outside of the energy sector, but BOE Governor Andrew Bailey said the Strait of Hormuz conflict has created additional upside risk to price stability. With that in mind, he said policymakers are prepared to raise interest rates if further signs of strengthening price pressure emerge. The BOE also provided an update to selling its bond holdings. It has decided to pause its uploading of the bonds, or gilts, until April so that it can assess selling the securities to the UK government. Looking beyond April, The BOE intends to eliminate its remaining 46 billion pounds of bonds or gilts, by the end of 2034.
The UK’s Office for National Statistics reported yesterday that prices were up 3.1% and 0.5% y/y and month over month (m/m), according to the Consumer Price Index. While both metrics matched the economist consensus estimates, they were hotter than July’s 2.9% and 03% lifts. Additionally, wholesale inflation picked up with the Producer Price Index input gauge showing items costing 6.1% and 0.3% more y/y and m/m. In July, the gauge depicted a y/y 5.8% ascent and a 0.8% m/m decline. Factory gate prices, furthermore, were 3.7% and 0.7% higher y/y following July’s 3.3% and 0.4% climbs.
Singapore’s non-oil exports in August jumped 46.2% y/y, a notable acceleration from July’s 24.1% and substantially stronger than the economist consensus estimate for a 35% expansion, according to Enterprise Singapore. The metric, which received a strong boost from AI electronics, pushed the country’s trade surplus up from SG $10.98 billion in July to SG $13.78 billion. Non-electronic exports were up 12% while shipments abroad of electronics surged 131.8% following July’s 112% ascent. In the electronics category, integrated circuits, disk media products and personal computers sales to foreign customers were 90.9%, 290.2% and 237% higher than in August 2025. In other sectors, specialized machinery, non-monetary gold and medical apparatuses expanded by 57.7%, 67% and 22.1%, respectively. The US increased its purchases of the country’s electronics by 324.4% y/y, a slight moderation from July’s 378.7% expansion. Other countries with strong electronics purchases included Indonesia, India, South Korea and Taiwan.
Canadian manufacturers jacked up their prices by 13.5% y/y and 1.3% m/m in August following their 12.3% and 0.3% y/y and m/m July hikes, according to Statistics Canada and the Industrial Producer Price Index. At the same time, raw material costs as measured by the Raw Materials Price Index soared 22.8% y/y and 3.1% m/m following the 18.2% annualized gain and monthly 2.1% drop in July. Gate prices were pushed higher on a m/m basis by energy and petroleum rising 4%. Indeed, the IPPI ex energy and petroleum index was up only 0.8% with its ascent driven by higher sticker for non-ferrous metal products and chemicals. In a similar manner, input costs ascended due to crude energy products climbing 7.1% m/m in August.
New to Interactive Brokers?
Open AccountInformation posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from IBKR Macroeconomics, an affiliate of Interactive Brokers LLC, and is being posted with its permission. The views expressed in this material are solely those of the author and/or IBKR Macroeconomics and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
Futures, event contracts, and forecast contracts are not suitable for all investors. Before trading these products, please read the CFTC Risk Disclosure. For a copy, visit our Warnings and Disclosures Page.
Trading in digital assets, including cryptocurrencies, is especially risky and is only for individuals with a high risk tolerance and the financial ability to sustain losses. Eligibility to trade in digital asset products may vary based on jurisdiction.
Investments in certain commodities (precious metals) may be subject to significant price volatility and often involve risks related to market fluctuations, liquidity constraints, geopolitical events, and changes in global economic conditions that could adversely affect their value.
Related Articles



Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!