- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted October 8, 2026 at 1:29 pm
An uptick in violence across the critical Strait of Hormuz waterway is driving fuel costs north and pressuring Wall Street via loftier Treasury yields. Stocks are retreating broadly for the second consecutive session, again led south by rate-sensitive areas. The cyclically oriented Russell 2000 and Dow Jones Industrial benchmarks are suffering the heaviest losses while the S&P 500 and Nasdaq 100 decline to lesser degrees amidst 8 of the 11 principal sectors sinking. Fixed income, meanwhile, is being negatively affected by heavier oil prices, but weaker-than-expected initial unemployment claims and subdued continuing filings are tightening financial conditions with the curve climbing in bear-flattening motion led by the shorter tenors, which are most reactive to shifts in monetary policy projections than fiscal dynamics, longer-term inflation expectations and growth estimates. The increasingly restrictive landscape is squashing animal spirits while battering cryptocurrencies and non-energy commodities. Separately, a hawkish tilt in the credit complex and demand for safe-haven assets are causing the greenback to strengthen and boosting bids for equity volatility protection instruments. Prediction markets are experiencing engagement as well, especially as it relates to the upcoming Fed decision and subsequent midterm elections.
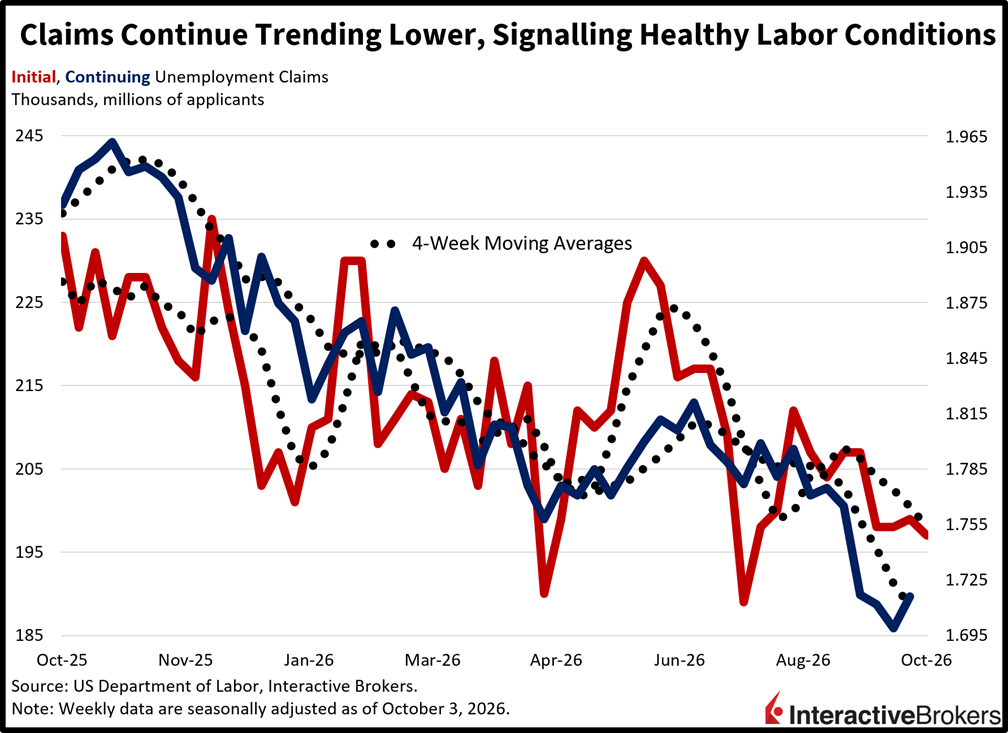
Unemployment claims were little changed and well behaved in this morning’s Department of Labor update, signaling the continuation of a stable employment cycle. Initial and continuing filings of 197k and 1.716 million during the weeks culminating on Oct. 3 and Sept. 26, arrived near estimates of 200k and 1.710 million as well as the 199k and 1.699 million from the prior print. Four-week moving averages sunk on both fronts, from 200.5k and 1.723 million to 197k and 1.711 million.
The brutal Treasury selloff of 2026 could be in its final days, as recent price action in the government debt complex suggests that bears may be exhausted. The 10- and 30-year maturities are down 10 basis points from their year-to-date highs reached just yesterday, with buyers stepping in to scoop the long-end whenever rates jump higher, irrespective of the loftier oil prices that we’re seeing. These early bullish changes in behavior are occurring as seasonal dynamics flip positive around the middle of October and just a few sessions prior to the beginning of the quarterly earnings cycle, which bodes well for Wall Street heading into the last months on the calendar. If sinking borrowing costs manifest alongside robust profit numbers, then that alone can spark rallies towards the finish line. But to post monumental gains from here that are consistent with an S&P 500 value of 8,300, we would need a resolution to the Middle East war that would bring West Texas Intermediate Crude back to $70 per barrel.
Credit availability for households declined slightly in the UK during the third quarter but was unchanged for businesses despite sinking slightly for small and medium-sized firms, according to the Bank of England’s credit survey. For households, the availability of secured and unsecured credit was expected to increase. Going forward, both forms of financing are expected to become more plentiful. The steady supply of corporate capital matched expectations. In other matters, demand for financing of house purchases fell but lenders anticipate a slight increase this quarter, a result of a larger volume of remortgaging. More broadly, overall demand for unsecured lending was unchanged despite expectations that it would tick higher. The use of credit cards was unchanged and is expected to be stable while other forms of unsecured loans increased marginally, a trend that is expected to continue. Among businesses, lending by small and medium-size companies sank but was stable among larger firms. On a cautious note, defaults on credit card financing and other unsecured loans grew and are expected to continue climbing this quarter. Conversely, defaults of secured household financing decreased and are expected to remain unchanged. Additionally, the default rate among businesses was unchanged.
New to Interactive Brokers?
Open AccountInformation posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from IBKR Macroeconomics, an affiliate of Interactive Brokers LLC, and is being posted with its permission. The views expressed in this material are solely those of the author and/or IBKR Macroeconomics and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
Futures, event contracts, and forecast contracts are not suitable for all investors. Before trading these products, please read the CFTC Risk Disclosure. For a copy, visit our Warnings and Disclosures Page.
Trading in digital assets, including cryptocurrencies, is especially risky and is only for individuals with a high risk tolerance and the financial ability to sustain losses. Eligibility to trade in digital asset products may vary based on jurisdiction.
Related Articles




Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!