- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted October 13, 2026 at 1:32 pm
Stocks are sinking for the second consecutive session as doubts concerning AI’s ability to power corporate earnings much further coincide with heavier fuel charges that are supporting lofty Treasury yields. Investors are indeed worried about the possibility for profit deceleration alongside restrictive financial conditions, as elevated interest rates could start to bite in the coming months. Ongoing Middle East violence that is bolstering crude prices, meanwhile, is blocking potential gains for the cyclically oriented parts of the market, which have previously dampened adverse impacts upon broad indices when the tech trade has buckled, like it is today. As a result of the weaker risk sentiment and increasingly challenging macroeconomic backdrop, 9 of the 11 US principal sectors are retreating as well as the four major equity benchmarks. This morning’s economic calendar, furthermore, failed to rally the bulls, as decreasing small-business optimism that missed expectations, rising existing-home sales that beat projections, and fast hiring from the weekly ADP-employment survey essentially fell on deaf ears, although it helped raise the short-end of the curve via strengthening labor momentum that widened the path for a Fed hike or two. Separately, the longer-dated tenors have been catching safe-haven bids resulting, in part, from a modest uptick in slowdown angst that is additionally weighing on the greenback. Elsewhere, cryptocurrencies are rallying, non-energy commodities are sliding, volatility protection instruments are reflecting heightening hedging demand and prediction markets are experiencing engagement.
Inflationary pressures, elevated interest rates and subdued worker supply caused small-enterprise optimism to weaken in September with the National Federation of Independent Business (NFIB) result of 97.9 missing the median estimate of 98 and arriving under August’s 98.7. Components within the gauge that reflected the heaviest declines were views on capital expenditures and the economic outlook, while investment intentions, current job openings, expected credit conditions and earnings trends saw more modest decreases. Conversely, revenue projections and plans to increase inventories countered some of the negative developments, while hiring momentum was unchanged. Meanwhile, when asked to identify the single-most-important problem, 26%, 20%, 11% and 11% of respondents cited the quality/availability of labor, high prices, taxes and a lack of sales.

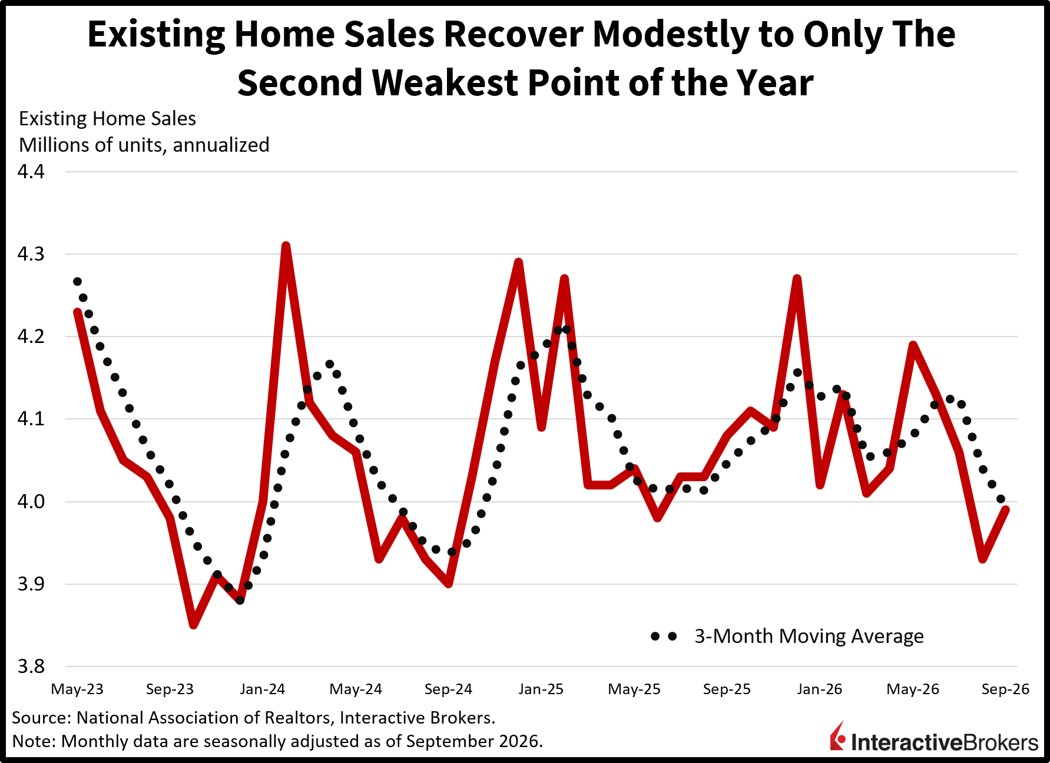
Existing home sales recovered modestly but only to the second weakest point of the year. August and September were the lowest figures of 2026, even as the latter month’s data, released this morning, reflected a 1.5% month-over-month (m/m) increase in the pace of transactions to 3.99 million seasonally adjusted annualized units. The result surpassed the 3.95 million anticipated and the prior period’s 3.93 million. Inventories climbed 1.9% m/m and 4.6% year over year (y/y) as prospective sellers listed properties, although the rate of closings remained subdued amidst elevated rates and valuations that rose 1.3% y/y to a median price of $412,300. Indeed, the affordability gauge fell to 105.4, beneath the 106.7 from the same time 12 months ago. Across segments and regions, single-family homes saw activity rise 2% m/m; however, the condominium and cooperative category experienced a decline of 2.8%. The South and West produced m/m gains of 2.8% each, the Northeast sank 2.1% and the Midwest was unchanged.
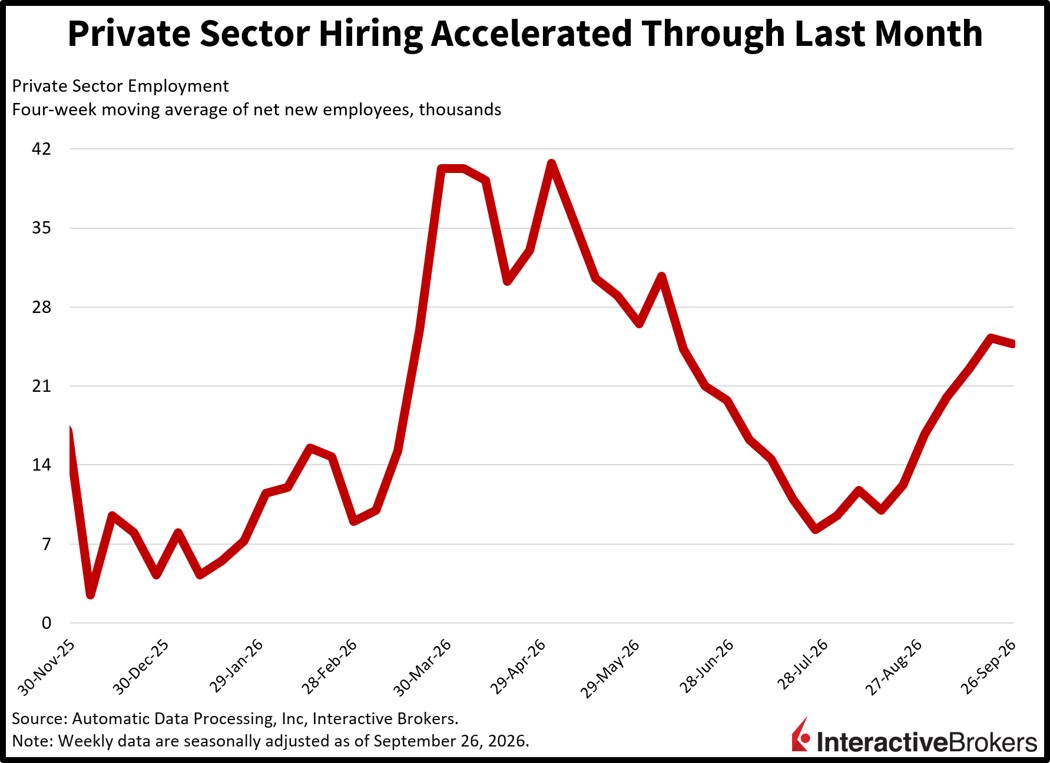
ADP’s weekly read on hiring momentum decelerated for the first time since early August, but labor conditions are still stable and healthy across the US economy. Indeed, the 24.75k total workers added on average in each of the four weeks that ended on Sept. 26 was robust, signaling monthly job growth of over 100k, and just slightly slower than the prior period’s 25.25k.
With corporate earnings growth in the nosebleeds amidst expectations for decelerating profit expansions in the coming quarters, investors want to feel optimistic about 2027 prior to adding meaningful exposure. The current slowdown anxiety paired with lofty interest rates is the primary reason, in my view, that stocks have been relatively flat in the past ten weeks, as we continue to trade at the same levels as in early August. Meanwhile, tomorrow’s Consumer Price Index alongside incoming quarterly reports will provide evidence of the temperature of inflation as well as the buoyancy of revenues, incomes and margins, which together may signal favorable comps for cost pressures as we turn the calendar amidst disadvantageous reference points for bottom lines. Wall Street could digest an environment of weaker payouts and still post gains against the backdrop of looser financial conditions stemming from the Fed’s 2% objective being easier to get to in consideration of the average West Texas Intermediate charge in 2026 standing at around $87 per barrel.
UK retail sales weakened last month, a result of households continuing to use caution at cash registers as they brace for expected increases in bills and taxes, according to the British Retail Consortium. Sales were up only 1% y/y compared to the 12-month average of 1.5%. Additionally, the pace was slower than the 2.3% y/y growth that occurred in September 2025. The in-store non-food category performed worse. Its y/y growth of 0.1% was roughly 0.3 percentage points below the 12-month average. In the year-ago period, sales were up 0.5%. Overall non-food transactions, meanwhile, slowed from a 0.7% y/y growth rate in the year-ago period to 0.3% last month, but improved marginally from the 12-month average expansion of 0.2%. Food sales also decelerated the 2.5% y/y expansion slowing from 4.3% in September of 2025 and falling below the 12-month average of 3.1%. Unusually warm weather dampened demand for clothing and footwear, although back-to-school spending helped support sales. In other areas, the toy segment received a boost from the launch of Pokémon’s 30th anniversary products. Health and beauty products were also strong. The BRC maintains that the broader results illustrate how consumers have become increasingly selective.
The anemic sales have occurred as the UK is working on its next budget. While the country is seeking to increase defense spending and maintain spending on health care, doing so could require an additional £35 billion without cutting other items from the budget, according to a recent study from the Institute for Fiscal Studies. With soaring interests resulting from growing government deficits, AI companies issuing debt and intensifying inflations fears triggered by the US-Iran war, the UK is facing mounting pressure to show that it can get its finances under control. Chancellor John Healey is scheduled to release his spending plans on Oct. 28.
In another development, the International Monetary Fund (IMF) yesterday revised its 2026 UK GPD growth estimate upward to 1.3%. In July, the IMF said it anticipated growth of only 1%. Conversely, inflation is expected to average 3.3% this year, substantially exceeding the Bank of England’s target.
Gate prices for Japanese goods producers sank 0.3% m/m in September but were still up 6.8% y/y, according to the preliminary Producer Price Index, which is also called the Corporate Goods Price Index. The monthly print was the second negative result since August 2025. The recent decline followed a drop of the same extent as during this past August, and it missed the economist consensus estimate for a 0.5% ascent. The y/y number eased from 7.6% in the preceding month. Economists anticipated that September’s wholesale charges would increase at the same pace as in August.
The m/m drop resulted from the following two categories having the stated softening in stickers:
Businesses were able to raise prices in other categories, but only by negligible amounts, or less than 0.1%.
On a more positive note for producers, companies hiked export charges by 1.4% m/m while import gate prices were up 1%. Among exports, the electric and electronic products category and the group consisting of primary products and manufactured goods fetched 0.8% and 0.3% more m/m in foreign markets. Within imports, petroleum, coal and natural gas became 0.69% more costly.
New to Interactive Brokers?
Open AccountInformation posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from IBKR Macroeconomics, an affiliate of Interactive Brokers LLC, and is being posted with its permission. The views expressed in this material are solely those of the author and/or IBKR Macroeconomics and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
Futures, event contracts, and forecast contracts are not suitable for all investors. Before trading these products, please read the CFTC Risk Disclosure. For a copy, visit our Warnings and Disclosures Page.
Trading in digital assets, including cryptocurrencies, is especially risky and is only for individuals with a high risk tolerance and the financial ability to sustain losses. Eligibility to trade in digital asset products may vary based on jurisdiction.
Related Articles



Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!