- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted November 10, 2026 at 1:18 pm
This morning, markets were eagerly awaiting the October CPI report. Put simply, it was a disappointment. Both headline and Core readings exceeded economists’ consensus by 0.1% on a month-over-month basis. Short-term interest rates soared, with 2-year Treasury yields leaping by 18 basis points, thanks to increased perceptions about the likelihood of a rate hike at the December FOMC meeting. Comments yesterday and today by two prominent Fed officials added to the concern. So far, though, stock traders are less perturbed than their fixed income counterparts. Let’s unpack.
Headline CPI rose by 0.4% in October, below last month’s 0.6% rise but above the 0.3% consensus; the Core CPI rose by 0.3%, unchanged from last month and also 0.1% above the 0.2% consensus. The Bureau of Labor Statistics (BLS) did not make a year-over-year change available because the government was shut down one year ago, but when we annualize the recent numbers, they are clearly well above the Fed’s 2% target. Using the actual index levels, we find the following:
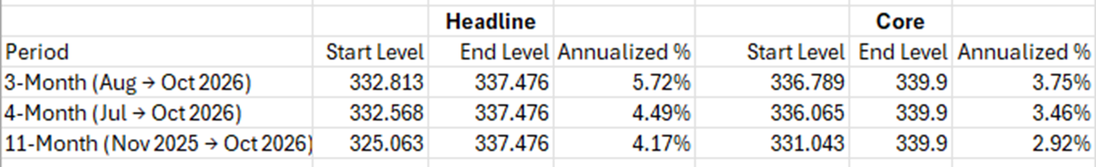
Sources: bls.gov, Bloomberg, Interactive Brokers
(Remember, the Consumer Price Index is a measure like the S&P 500 (SPX), even though we focus on the monthly and yearly changes to that index.)
The most recent bout of Fed-speak added to the concerns brought about by the data. Markets were already on edge somewhat after comments by Governor Christopher Waller indicated yesterday not only that he favored a hike in December but also that a half-point boost may be necessary. Those comments took stocks off their highs just before yesterday’s close but barely dented the overall enthusiasm. Today’s CPI report made it very difficult to refute those comments. Then, before 11 AM this morning, Dallas Fed President Lorie Logan reiterated her opinion that two future rate hikes would be necessary, and that they may need to arrive more rapidly than she previously thought. We expect to hear from Vice Chair Jefferson and New York Fed President Williams, among others, later this week.
Futures markets and prediction markets both quickly boosted their probabilities for hikes at the December 9 FOMC meeting. They are in general agreement. The CME FedWatch shows 100% likelihood for a hike in December, with 89% of futures traders pricing in a 25 bp hike and 11% pricing in a 50 bp bump. Yesterday, the expectation for a single hike was 84%. IBKR Prediction Markets show an 85% chance for a single hike and 11% for a double-sized boost, though there is still a 4% “Yes” for no hike. More importantly, futures markets are pricing in one more hike by April 2027 than they were yesterday. That explains the significant bump in short-term rates. (For reference, the next CPI report is scheduled for December 10,while the next PCE report is due on November 25, the day before Thanksgiving.)
I will assert that stocks are putting in a decent performance, all things considered. Remember, if markets are having a difficult time pricing low-risk assets, such as short-term fixed income, they are unlikely to have an easy time pricing riskier assets like equities. Major indices were attempting to claw back their early losses – SPX had briefly returned to positive territory shortly after 10 AM – but Logan’s comments took them to new lows. Nonetheless, the current declines of 0.8% for SPX and 1.3% for the Nasdaq 100 (NDX) pale in comparison to yesterday’s respective gains of 2.35% and 3.4%. One prominent dour spot remains. Nvidia (NVDA) is down by more than 6% today after yesterday’s 4.27% drop. As we recently noted, dip-buying is proving much more successful when a drop stems from an overreaction to otherwise decent news than when the news causes institutional investors to reevaluate a company’s prospects. As we work through the recent volatility – and yes, yesterday’s market bounce counts as volatility – that seems to be an important factor to keep in mind.
New to Interactive Brokers?
Open AccountAlready an Interactive Brokers Client?
Request Trading PermissionThe analysis in this material is provided for information only and is not and should not be construed as an offer to sell or the solicitation of an offer to buy any security. To the extent that this material discusses general market activity, industry or sector trends or other broad-based economic or political conditions, it should not be construed as research or investment advice. To the extent that it includes references to specific securities, commodities, currencies, or other instruments, those references do not constitute a recommendation by IBKR to buy, sell or hold such investments. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
The views and opinions expressed herein are those of the author and do not necessarily reflect the views of Interactive Brokers, its affiliates, or its employees.
Related Articles



Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!