- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted September 30, 2026 at 12:47 pm
At 8:30 ET this morning, all eyes were glued to screens for the release of the Federal Reserve’s preferred inflation measure, the Core PCE Price Index, which arrived amidst a slew of other data. We got a pleasant surprise when the monthly rise for August was 0.2%, below the 0.3% consensus. Furthermore, the yearly change was 3.0%, aided by some revisions, which was well below the 3.3% consensus estimate. Stocks, understandably, are reacting positively to the report; bonds, not so much.
Before focusing on market performance this morning, let’s look at the rest of the numerous economic reports that were released today. The labor market got a positive surprise when the ADP Employment Change showed a 90,000 increase, which was above the 75,000 expectation. Along with the PCE figures, we also saw economic strength in the third and final estimates of Q2 GDP, Personal Consumption, the GDP Price Index, and Core PCE Price Index. All were expected to remain unchanged from the prior estimate, but 2Q GDP rose to 2.2% from 1.5%; Personal Consumption rose to 3.8% from 3.4%; the GDP Price Index fell to 6.1% from 6.4%; and the Core PCE Price Index rose by 3.3%, less than the prior 3.6%. The positive economic sentiment got a final chef’s kiss at 9:45 ET when the MNI Chicago PMI soared to 58.8, well above both the 51.0 estimate and last month’s 47.1.
The negative portion of the 8:30 data dump came in the August reports on Personal Income, Personal Spending, and Real Personal Spending. Personal Income rose by only 0.2%, missing the 0.5% consensus, while July was revised down to 0.3% from 0.4%. That was well below the increases in both Personal Spending (an increase of 0.9%, as expected) and Real Personal Spending (0.6%, above the 0.5% consensus). It doesn’t take much advanced math to see why consumer sentiment is depressed about concerns regarding affordability when we are collectively increasing our spending far faster than our incomes are rising.
When we synthesize all that economic data, it is relatively easy to understand why stocks moved higher. We have said many times that investors should be rooting for a strong economy rather than one that requires monetary accommodation. The debate, of course, has long since moved on from rate cuts to rate hikes, but a better-than-expected key inflation measure should reduce the need for a near-term rate increase. To that end, we have seen expectations for a hike fall once again. They slipped yesterday after New York Fed President John Williams suggested that the next hike could wait until December. I had always thought that a rate hike less than a week before the midterms seemed like a long shot at best, but the markets disagreed with that opinion. (That said, I thought that a September hike would be politically untenable until the data proved otherwise.)
On Monday, CME FedWatch showed a 70% chance for an October hike. That fell to about 50% yesterday and 39% today. The move on IBKR Prediction Markets was nearly identical, as the chart below shows:
IBKR Prediction Markets for “Number of Fed Rate Hikes in October”, 1-Month
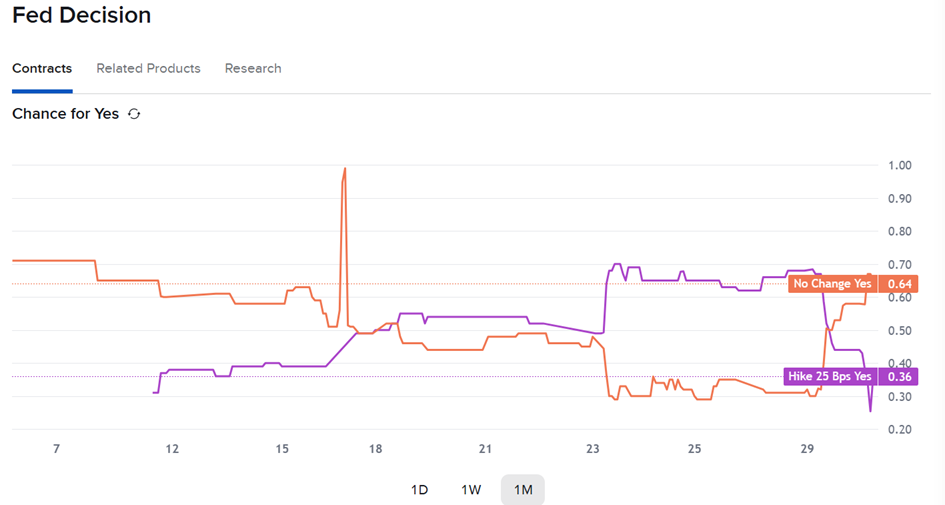
Source: IBKR Prediction Markets
The upward move in equities was therefore predictable. The combination of a strong economy and reduced expectations for rate hikes is as good a reason as any for a rally. Never mind that the rally is once again tech-led and otherwise mixed. Solid gains in technology, communications, and energy make up for the fact that every other S&P 500 (SPX) sector is lower except for a slight increase in financials. NYSE advances and declines are roughly equal, and there are 36 more decliners than gainers in SPX. This fits with the patterns we described yesterday, though with more solid gains in the key headline metrics.
Bonds remain problematic though. A strong economy can keep inflation lingering, but the bigger issue seems to be psychological. It appears, quite frankly, that few bond traders want to be long into the end of the quarter. We often think of equity investors being driven by momentum and the desire for window dressing around reporting periods, but so are bond investors. They’re human too, just maybe a bit more pessimistic than their stock market counterparts. If that is the case, we could see an oversold bounce when the calendar turns tomorrow, but that will require some assistance from Friday’s employment report. Stay tuned.
The analysis in this material is provided for information only and is not and should not be construed as an offer to sell or the solicitation of an offer to buy any security. To the extent that this material discusses general market activity, industry or sector trends or other broad-based economic or political conditions, it should not be construed as research or investment advice. To the extent that it includes references to specific securities, commodities, currencies, or other instruments, those references do not constitute a recommendation by IBKR to buy, sell or hold such investments. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
The views and opinions expressed herein are those of the author and do not necessarily reflect the views of Interactive Brokers, its affiliates, or its employees.
Futures, event contracts, and forecast contracts are not suitable for all investors. Before trading these products, please read the CFTC Risk Disclosure. For a copy, visit our Warnings and Disclosures Page.
Event Contracts are only available to eligible clients, 21 years and older, of Interactive Brokers LLC, Interactive Brokers Canada Inc., Interactive Brokers Hong Kong Limited, Interactive Brokers Ireland Limited and Interactive Brokers Singapore Pte. Ltd. ForecastEx Forecast Contracts on US election results are only available to eligible US residents.
Displayed outcomes and prices are based on real-time market sentiment from ForecastEx LLC, an affiliate of IB LLC, as well as other CFTC-registered DCMs, including Kalshi and CME. For more information, see ibkr.com/realfex Note: Real-time market sentiment updates are only active during exchange open trading hours. Updates to current market sentiment for overnight activity will be reflected at the open on the next trading day. This information is not intended by IBKR as an opinion or likelihood of a potential outcome.
This is commentary on economic, political and/or market conditions within the meaning of CFTC Regulation 1.71, and is not meant provide sufficient information upon which to base a decision to enter into a derivatives transaction.
Interactive Brokers LLC is a CFTC-registered Futures Commission Merchant and a clearing member and affiliate of ForecastEx LLC (“ForecastEx”). ForecastEx is a CFTC-registered Designated Contract Market and Derivatives Clearing Organization. Interactive Brokers LLC provides access to ForecastEx Forecast Contracts for eligible customers. Interactive Brokers LLC does not make recommendations with respect to any products available on its platform, including those offered by ForecastEx.
Related Articles


Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!