- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted September 29, 2026 at 10:05 am
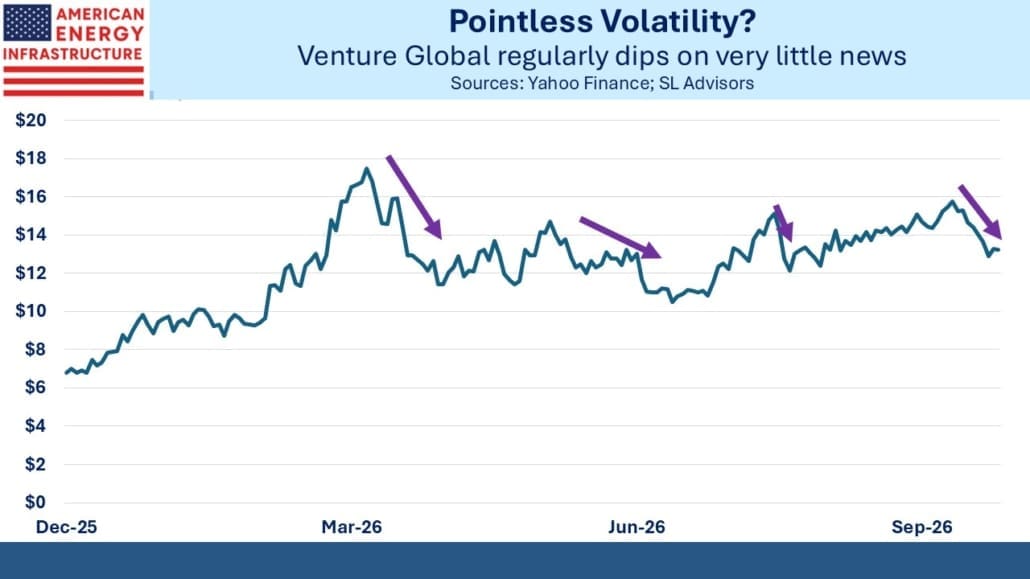
Market making in Venture Global (VG) must be a profitable business. More than most stocks, its price often follows a manic-depressive ride turning on the plausibility of presidential comments about negotiation with Iran. Following each dip as traders quickly conclude Trump’s tweets on Truth Social are based more on hope than substance, the stock rebounds. It’s dropped more than 15% in a month four times this year.
VG’s prospects improved once Qatar was forced to stop shipments of LNG. That is pretty much all investors need to consider other than the short term profit opportunities from the liquefaction capacity they can access that’s not already committed.
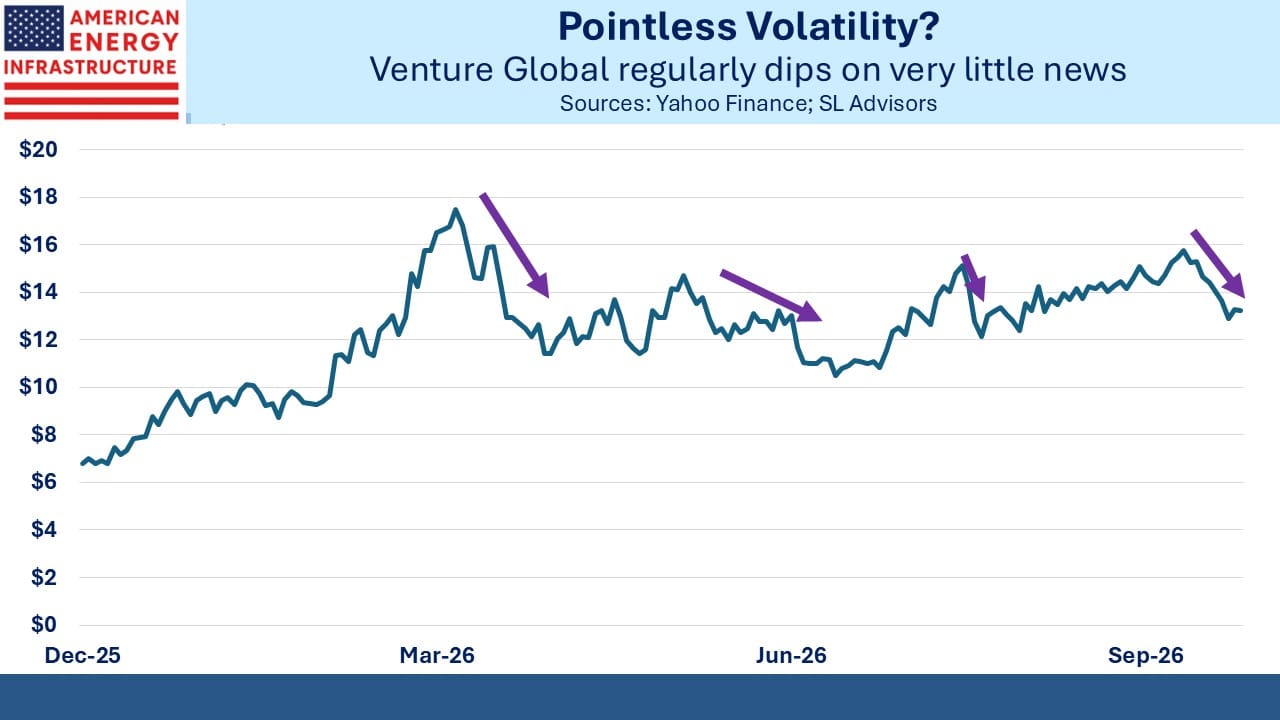
Last week as US energy exporters reeled from another sentiment shift around negotiations, VG dipped below $13, a level it easily exceeded in early March on its way to a high for the year of $17.46 reached on March 27. VG’s business prospects since then have only improved. It’s doubtful Qatar was warning its expectant buyers of LNG that there would still be no shipments six months later. If you want your LNG delivered on time, better to buy American.
But the market has done what markets do, and some perceived last week’s dip as an opportunity.
Predictably, President Trump has thrown his support behind a ban on diesel exports, having already told Ukraine’s President Zelenskyy to stop bombing Russian refineries. This is the proximate cause of the global shortage with the other being the loss of Persian Gulf exports of refined products.
The US produced 4.8 Million Barrels per Day (MMB/D) of Distillate Fuel Oil last year, which includes both diesel and heating oil. We consumed 3.9 MMB/D, exporting the balance. We do import a small amount, mostly in New England from Canada. Distillate Fuel Oil represents 18-20% of domestic petroleum products demand.
The challenges in a ban on diesel exports include that diesel that would be redirected internally is produced near the Gulf Coast where it can be loaded onto ships. There isn’t the pipeline infrastructure readily available to move it elsewhere in the country.
The 1920 Jones Act, which often impedes efforts to move hydrocarbons on water within the US, mandates that goods moved between American ports must travel in ships that are US owned, built and crewed. It’s why Boston imports LNG; left wing energy policies have prevented adding pipeline capacity linking them to Pennsylvania. Instead, it comes from foreign countries because there are no Jones Act-compliant LNG tankers that could ship it from the Gulf coast.
During WWII the country was divided into Petroleum Administration for Defense Districts (PADDs) and the EIA still uses them. PADD1 includes New England. Its imports of distillate fuel oil rise in the Fall/Winter, making this an inopportune time to disrupt their supply.
These imports come from foreign sources, and since the impact of an export ban is likely to push foreign diesel prices up, this region would likely see higher, not lower prices at least initially.
Overall, the friction to the movement of existing diesel fuels caused by an export ban would reduce the expected price benefit. There would be little point in investing in new pipelines to transport diesel from Gulf coast refineries to, say, New England because of the temporary nature of the ban.
Trump’s best bet might be to voice support for a ban without doing much to implement one. Energy Secretary Chris Wright has suggested an export ban might be voluntary, which would allow the Administration to claim some action while avoiding blame for any resulting price distortions.
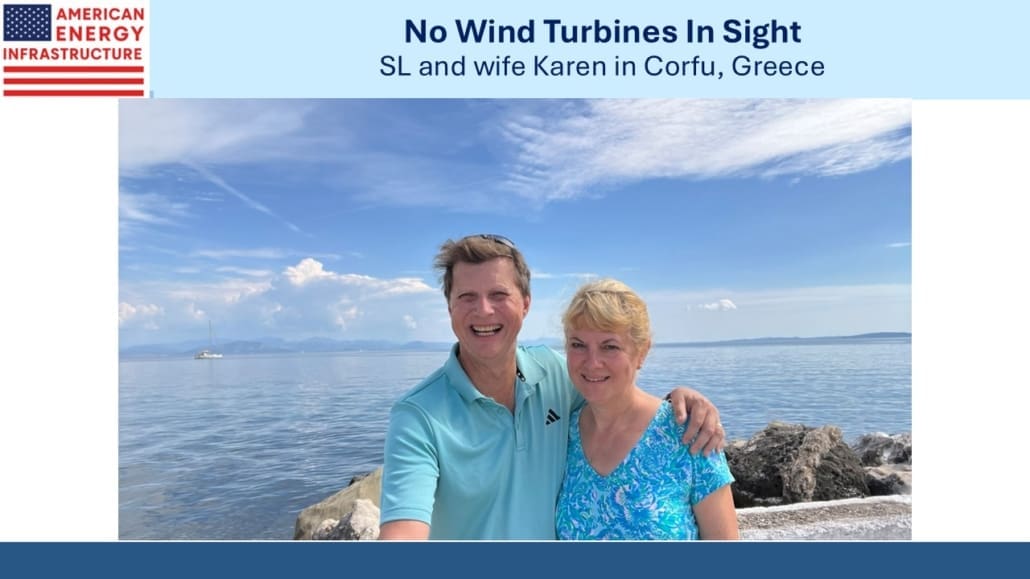
The Mediterranean vistas from Corfu, where we spent a few days last week, are mercilessly unsullied by wind turbines. Windpower might seem a logical choice for a Greek island with no local sources of coal or gas. In fact, there are no power plants at all on Corfu, which draws almost all its power from the Greek mainland via undersea cables.
EVs are surprisingly uncommon – Greece EV penetration is barely a third of the EU average. The fleet of cars is older than average – Greeks keep their cars longer because they’re poorer. And the charging infrastructure is not as well developed as elsewhere.
Corfu’s energy mix for electricity mirrors Greece since that’s where its power comes from. Natural gas is the biggest source at 37%, not far behind the US. Wind is 22% although as mentioned not from anywhere near Corfu.
Greece’s gas imports have been rising. Over half of their gas consumption is delivered as LNG, and the US is around three quarters of that. In June Greece’s gas importer Atlantic-SEE LNG Trade, expanded an LNG deal with VG.
They’re taking a longer-term view than some of the recent traders in VG stock.
—
Originally Posted September 27, 2026 – Venture Global Moves More Than Needed
Please go to following link for important legal disclosures: https://sl-advisors.com/legal-disclosure
SL Advisors is invested in all the components of the American Energy Independence Index via the ETF that seeks to track its performance.
Information posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from SL Advisors and is being posted with its permission. The views expressed in this material are solely those of the author and/or SL Advisors and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
Related Articles


Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!