- Solve real problems with our hands-on interface
- Progress from basic puts and calls to advanced strategies
Interactive Options Course
Posted August 21, 2026 at 1:28 pm
Stocks are coming back after a 20-month high in the services PMI bolstered the economic outlook at a time when investors have been worried that contracting payrolls and declining retail sales in July could mark the beginning of a cyclical slowdown. The preliminary August numbers reflected a surge in hiring and in consumption, which are strengthening GDP and corporate earnings prospects; however, the buoyancy is precipitating loftier yields. The Treasury curve is climbing in bear-flattening fashion led by the monetary policy sensitive shorter duration maturities as the argument to pause weakens against the backdrop of this morning’s print signaling a reacceleration in payroll expansions and in household spending. Indeed, the publication, arriving on the heels of yesterday’s softer-than-expected initial unemployment claims, is countering the notion that the labor market requires looser financial conditions to thrive. Geopolitics are additionally weighing on fixed-income assets today, as rising oil prices continue to support elevated inflation expectations and heavier borrowing costs as a result. Still, all four major domestic equity benchmarks are shrugging off higher rates as they advance amidst a broad recovery consisting of 10 of the 11 principal sectors participating in the gains. The revival in animal spirits has cryptocurrencies rallying, with bitcoin jumping to a three-month high just short of 80k, while commodities and prediction markets are broadly catching bids. Elsewhere, the greenback is nearly flat while volatility protection instruments are seeing lighter premiums in light of a risk-on session on Wall Street featuring weaker hedging demand.
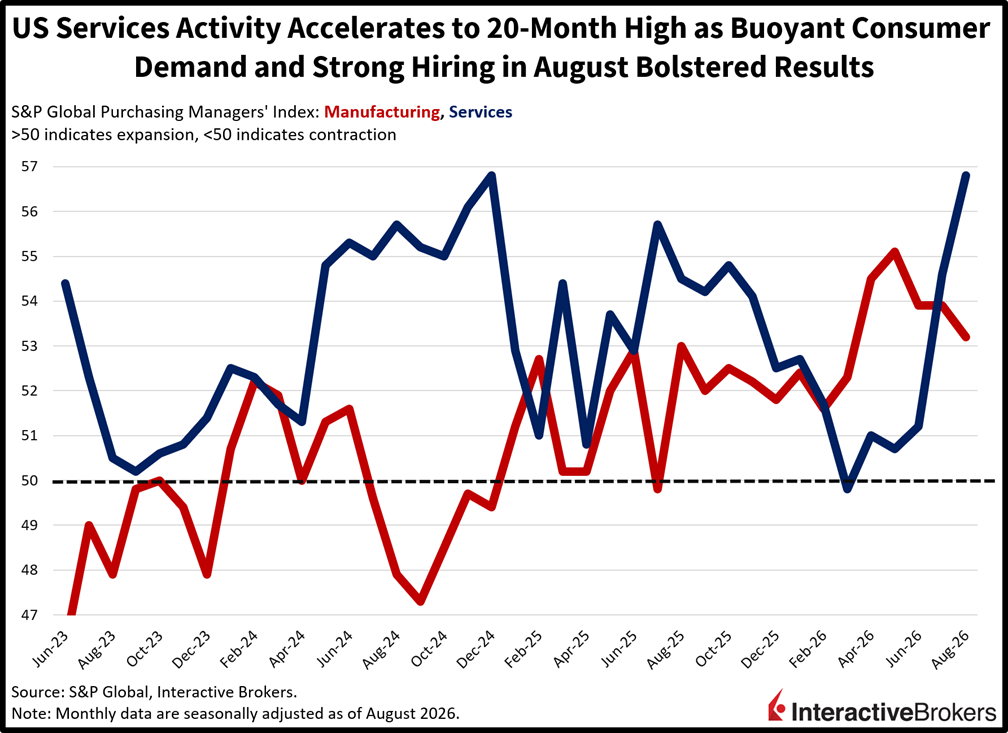
The US economy’s growth accelerated this month, according to this morning’s flash Purchasing Managers’ Indices from S&P Global. The reports signaled stronger consumer demand, a surge in hiring, cooling price pressures and the third consecutive improvement in business confidence. While both services and manufacturing expanded strongly with headline results of 56.8 and 53.2, well above the expansion-contraction threshold of 50, the outperformance was led by the former sector. The figures compare to the median estimates of 54 and 53.9 and the previous month’s 54.6 and 53.9. Factories could be signaling an AI slowdown ahead, however, as the category reflected sluggish inventory buying and it has decelerated in every print since June. Inflationary forces were subdued even as input costs remained heavy, pointing to the potential for productivity improvements that could sustain profit margins.
The Treasury’s debt buyback announcement has suffered from bad timing, as the resulting plunge in yields was totally offset by mounting geopolitical tensions and terrific economic data. But Secretary Scott Bessent has another opportunity to tame the pressure on interest rates this Monday with a press conference to discuss financial sanctions on Iran and the department’s plans for subduing borrowing costs. While Wall Street has so far deemed Washington’s efforts as insufficient irrespective of the countering factors like rising oil prices and robust activity numbers, there could be more measures in the pipeline, and a quantitative easing program from the Fed would certainly help quell the pain at the long end of the curve. Finally, decelerating inflation doesn’t justify a 5-handle on any of the complex’s maturities and buying duration currently provides an attractive risk-reward profile, in my opinion.
Economic activity in Europe expanded this month at a slightly faster pace than in July with improving manufacturing conditions pushing the S&P Global Flash Eurozone PMI Composite Index up 0.1 point to 52.1, a nine-month high and above the 51.7 economist consensus estimate. The services PMI was unchanged at 51.7, which surpassed expectations for 51.5 while the manufacturing gauge moved up to 52.8. Economists anticipated a result of 51.8 following June’s 51.9 level. In another positive development, the manufacturing output PMI moved from 52.9 to 53.4. Among manufacturers, new export business expanded for the first time in four-and-a-half years. More broadly, orders grew as companies increased their inventories to hedge against a potential continuation of supply chain disruptions as a result of the US-Iran war. Strong demand for AI-technology provided an additional manufacturing tailwind. Germany, which is Europe’s largest economy, accounted for much of the improved manufacturing result with the sector growing at its fastest pace since January 2022. Also this month, manufacturers in Europe added workers in response to increased demand for products. It was the first time this year that payrolls expanded. In other areas, input price pressures eased slight but were still higher than prior to the US-Iran War. Output inflation also slowed, but this change was attributable primarily to Germany. Looking ahead, the outlook for output in the coming year sank to a three-month low that was below the metric average. Manufacturers were more upbeat while confidence among services providers waned.
The growth of business activity in the UK accelerated in August to its fastest pace in four months with the services sector contributing to the S&P Flash PMI Composite Output Index climbing from 52.2 in July to 52.5 and surpassing the 51.6 economist consensus estimate. The manufacturing PMI and output gauges, however, fell from 51.9 and 52.9 to 51.5 and 51.2, respectively. Economists anticipated that the manufacturing PMI would fall only 0.3 points to 51.6. The slowing growth in manufacturing was more than offset by the services PMI climbing from 52.1 to 52.8 and easily surpassing the 51.8 economist consensus expectation. It is the highest level since February.
Loftier levels of new business and consumer spending in the services sector more than offset weaker export sales. Despite the strong services publication, input cost inflation was a headwind. Survey respondents said suppliers tried to pass higher transport costs from pricy fuel onto to companies. Some respondents reported higher food, technology, labor and utility costs. Businesses were able to pass some of the higher costs onto clients.
Employment levels continued to fall, marking the 23rd consecutive month of contraction but it was the smallest decline since October. Going forward, expectations for the year ahead improved and optimism among both manufacturers and services business hitting the highest level since February. Indeed, some evidence points to stronger order books and improving economic conditions domestically and abroad.
Retail sales in the UK grew 2.3% year over year (y/y) in July by volume but slipped 0.9% month over month (m/m), weakening substantially from the 5% and 0.9% y/y and m/m ascents in June.
The volumes also missed the -0.4% and 2.2% m/m and y/y rates anticipated by economists. For the m/m report, automotive fuel was up 3.8% while food stores and other non-food stores experienced 0.5% and 0.3% expansions. Categories with declines and the extent of the changes included the following:
Japan PMI Depicts Broad Expansion
Japanese business activity grew at the fastest rate in six months with the S&P Flash Japan Composite PMI Output Index climbing from 52.7 in July to 53.4 this month. The services gauge went from 51.2 to 52.3 and the manufacturing index, after hitting 54.5 in July, ascended to 55.1. The manufacturing output gauge, however, slipped from 56.3 to 56.1.
New to Interactive Brokers?
Open AccountInformation posted on IBKR Campus that is provided by third-parties does NOT constitute a recommendation that you should contract for the services of that third party. Third-party participants who contribute to IBKR Campus are independent of Interactive Brokers and Interactive Brokers does not make any representations or warranties concerning the services offered, their past or future performance, or the accuracy of the information provided by the third party. Past performance is no guarantee of future results.
This material is from IBKR Macroeconomics, an affiliate of Interactive Brokers LLC, and is being posted with its permission. The views expressed in this material are solely those of the author and/or IBKR Macroeconomics and Interactive Brokers is not endorsing or recommending any investment or trading discussed in the material. This material is not and should not be construed as an offer to buy or sell any security. It should not be construed as research or investment advice or a recommendation to buy, sell or hold any security or commodity. This material does not and is not intended to take into account the particular financial conditions, investment objectives or requirements of individual customers. Before acting on this material, you should consider whether it is suitable for your particular circumstances and, as necessary, seek professional advice.
Related Articles

Join The Conversation
For specific platform feedback and suggestions, please submit it directly to our team using these instructions.
If you have an account-specific question or concern, please reach out to Client Services.
We encourage you to look through our FAQs before posting. Your question may already be covered!